 Credentials

News flash: The median price drivers now pay for annual car insurance coverage is $2,079. With grocery, utility, gasoline, and other costs rising and consumers seeking to save dollars wherever they can, it’s not surprising that many policyholders are opting to lower their insurance coverage levels (often by sacrificing collision coverage).[1]
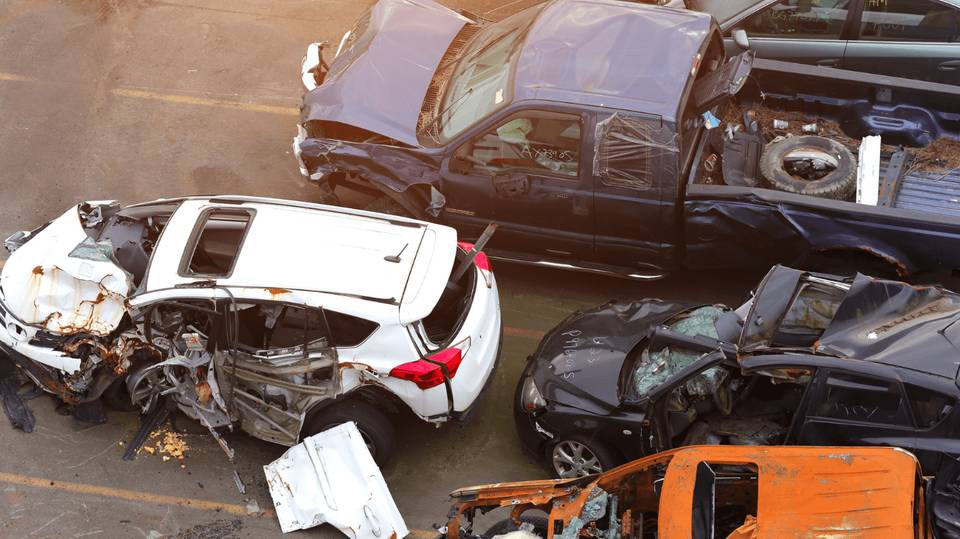
For some, reducing coverage is the right call. But while this strategy can lower your premium, it could also leave you financially vulnerable. Just imagine being involved in a multi-car crash with bodily injury claims and a totaled car, but you only have minimum coverage that’s legally required in your state. It’s an outcome that could drain five to six figures from your bank account.
Take the time to better understand the risks behind dropping coverage, scenarios where it’s recommended, why you shouldn’t rely on state minimum coverage, and alternative ways to pay less.