Who Inherits the Homeowners Insurance When Someone Dies?

Author profile picture
Contributing Writer | Personal Finance and Insurance

Erik J. Martin is a Chicagoland-based freelance writer who writes on insurance and finance topics for a variety of publishers, including The Chicago …

Author profile picture
Senior Editorial Manager

Susan is a licensed insurance agent and has worked as a writer and editor for over 10 years across a number of industries. She has worked at The Zebr…

Credentials
  • Licensed Insurance Agent — Property and Casualty
Author profile picture
Insurance Analyst

Beth joined The Zebra in 2022 as an Associate Content Strategist. A licensed insurance agent, she specializes in creating clear, accessible content t…

Credentials
  • Licensed Insurance Agent — Property and Casualty
  • Associate in Insurance (AINS)
  • Professional Risk Consultant (PRC)
  • Associate in Insurance Services (AIS)
generations family hands inherit

When someone in your family passes away, it can trigger a cascade of financial complications, particularly insurance worries, at a difficult time when you’re least prepared to handle them. Life and health insurance policies take priority, but don’t overlook your loved one’s homeowners insurance. Many families don’t realize that a homeowners policy doesn’t automatically transfer to a surviving spouse or beneficiary, or that serious coverage gaps can surface during estate settlement, probate, and property transfers.

Let’s take a deeper dive into what to expect with a deceased person’s homeowners policy, how force-placed insurance works, vacancy vulnerabilities to avoid, and what you should do immediately after they pass away.
The Coverage Question Nobody Thinks to Ask

When a policyholder passes away (the “decedent”), surviving families often face many key questions about funeral arrangements, estate settlement, and the home they leave behind. But there’s another important question that often goes overlooked: What happens to their homeowners insurance?

Many people assume this coverage continues seamlessly following the death. But it often does not, and complications can arise depending on how the property is titled, who’s named on the policy, and how quickly the estate is settled.

“Most think the policy is tied to the property, but it’s actually tied to the person who bought it. When that person dies, the legal relationship between the named insured and the home shifts, eventually creating a gap the policy may not have been written to cover,” says Anna Blood, a family law and estate planning attorney in North Carolina.[1] 

Note that the “named insured” is the person specifically listed by name on the policy who owns the insurance contract, pays for the coverage, and has full rights to manage claims and benefits.

What Happens to the Policy Immediately After a Death?

Look closely at your homeowners policy and you’ll likely find a death clause listed. This should indicate that when the named insured dies, coverage can continue for the household members or relatives who were living in the home at the time of death, or for the named insured’s executor or legal representative. 

Things get more complicated depending on how the home was titled. If it was owned solely by the person who died, or held under a titling arrangement like tenancy in common, the home typically has to go through probate before ownership can transfer. And if the insurance policy was only in the deceased person’s name, it may not automatically cover the surviving spouse, heir, or whoever is handling the estate. Titling situations can get complicated quickly, and an estate attorney is a valuable resource for sorting out the details.

“That means any insurance claim filed by someone not named on the policy can be denied, even if they are the rightful heir,” cautions Blood.

Be aware that if the home is titled as tenancy by the entirety, joint tenancy with survivorship, a living trust, or what’s called a Lady Bird deed, the real estate title bypasses probate and should transfer directly to the surviving spouse or heir, according to Michigan attorney Matthew Clark.[2] (Note: If your property is included in a living trust, the trust should be listed as an additional insured on your homeowners policy.)

Important caveat, however: Even if the home avoids probate, the insurance policy doesn’t automatically transfer with the title. To keep the home protected, the spouse, heir, or legal representative must immediately notify the insurance company and update or rewrite the policy or create a new policy in their name.

Janet Ruiz, director of Strategic Communication for the Insurance Information Institute, cautions that delays can create lapses in coverage.[3]

“Insurance issues often arise when a property remains in probate or ownership questions remain unresolved for months. For example, an adult child may inherit a home but fail to notify the insurer while the estate is being settled. If significant changes occur, such as long-term vacancy or occupancy changes, coverage restrictions could apply,” she says. “Prompt communication with the carrier helps ensure appropriate protection remains in place.”

state laws
Estate and insurance laws vary significantly by state, and every situation is different.

This guidance is meant to give you a general picture of what to expect, not to replace advice from a licensed attorney, financial advisor, or specific insurer. If you’re navigating a loved one’s estate, it’s worth a conversation with a local expert who knows your state’s specific rules.

The Force-Placed Insurance Trap

Let’s say homeowners coverage lapses on a property that’s still being financed. In this hypothetical, the mortgage lender can step in to purchase special coverage called force-placed insurance. This protects the lender’s financial interest in the property.

“Your family’s furniture, liability, and equity get no coverage, and the premium costs far more,” Clark says, noting that the costs, paid by the surviving owner/heir, are often two to three times higher than a typical homeowners policy.[4] “Federal rules require the lender to send two written warnings before it charges the homeowner. But after a death, those warnings may go to an empty mailbox. Heirs should not wait for that letter. They can register with the loan servicer as a successor in interest and receive those notices themselves.”

You can bypass force-placed insurance by providing proof to the lender that sufficient and continuous coverage is in place.

Avoid These Vacant Home Risks

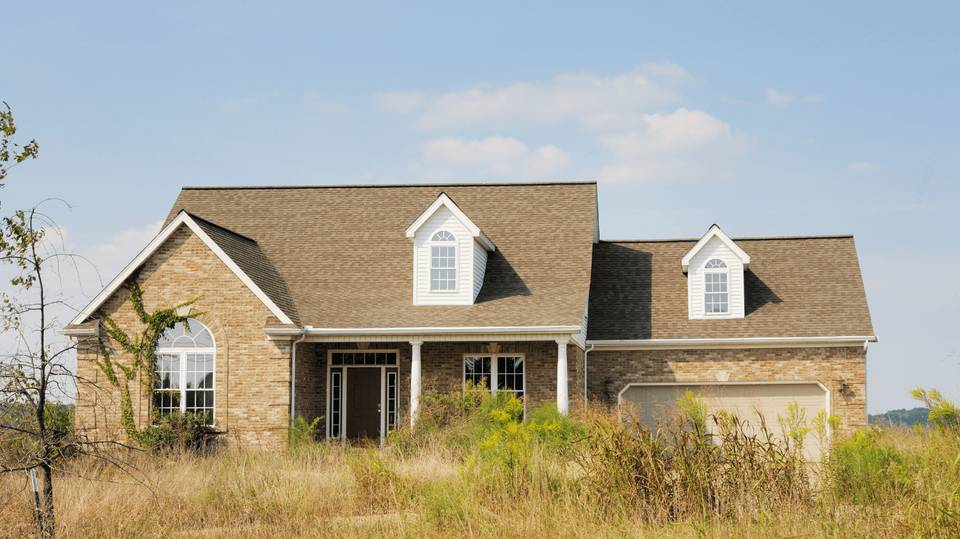
After the death, the property may sit empty while the estate is settled. That window of time can be especially risky.

“Problems such as water leaks, vandalism, theft, or maintenance issues can go unnoticed for extended periods,” says Ruiz. 

After the death, the property may sit empty while the estate is settled. That window of time can be especially risky.

What’s more, standard homeowners policies restrict or exclude coverage for these and other perils on a home that remains vacant for 60 consecutive days.

“Standard homeowners policies are written with the assumption that someone is regularly in the home to notice anything that may become an insurance claim,” Blood says. “If the home is sitting vacant and there’s a break-in, a burst pipe, or storm damage, who was there to notice? That’s why most insurance policies have a vacancy clause.”

To play it safe, you can purchase a vacancy endorsement from your carrier: an add-on to the existing policy that keeps coverage in place while the house stays empty.

“If the carrier refuses, your family needs a standalone vacant home policy, which can have higher premiums and cover fewer perils,” says Clark.

How to Transfer or Update Coverage

To protect your interests and shield the property following the death of a loved one, follow these best practices:
  • Confirm who is named on the insurance policy. Identify every named insured on the declarations page, as well as any mortgagee, and review the death clause listed in the policy.“
  • Immediately notify the homeowners insurance company of the death. Ideally, this should be done before probate begins.
  • Prepare to provide proof. The insurer may request a death certificate, legal documents, or other proof of authority if requested.
  • Learn the vacancy rules. “Ask how many days of vacancy are allowed before coverage is restricted or terminated,” Blood advises.
  • Be transparent with the carrier. Disclose whether the home is now occupied, vacant, rented, listed for sale, or under repair.
  • Update or replace the policy as needed. Ask the insurer whether the existing policy can be transferred to the surviving spouse, heir, estate, trust, or new owner, or whether a replacement homeowners, landlord, vacant-dwelling, or builder's-risk policy is required.
  • Make payments punctually. “Be sure premiums are paid on time during the estate administration period so that the policy doesn’t lapse for nonpayment,” says Blood.
  • Monitor the vacant property. Check in regularly at the home to ensure no theft or damage has occurred, and keep the heat on during winter to prevent water damage from frozen/burst pipes.

Frequently Asked Questions

Does homeowners insurance transfer to a surviving spouse? Chevron down icon

In many cases, a surviving spouse who is already a named insured on the policy can continue coverage with relatively few changes. But circumstances can vary depending on the policy and ownership structure. The family should work directly with the carrier to confirm coverage and make any necessary updates.

How long does homeowners insurance last after someone dies? Chevron down icon

Coverage typically continues through the end of the current policy term, and in many cases can be renewed in the name of the deceased’s estate while probate is being settled, as long as premiums are paid on time. That said, two things can cut coverage short: if the home sits vacant for more than 60 consecutive days, the policy may restrict certain protections, and once the property title officially transfers to a new owner, the carrier will require a new policy in that person’s name. The safest approach is to contact the insurer right away and ask specifically what coverage looks like during the transition period.

What is force-placed insurance and how do I avoid it? Chevron down icon

Force-placed insurance is coverage purchased by the mortgage lender on a deceased person’s financed property, but paid for by the survivors/heirs, when required insurance coverage on that property lapses. Its purpose is to protect the lender’s financial interest in the property, not the homeowner’s personal belongings or liability exposure. These policies often provide more limited protection and can be more expensive than standard homeowners insurance.

Does a vacant home need its own insurance policy? Chevron down icon

If a home will remain vacant for an extended time, standard homeowners coverage may not provide the level of protection needed. Depending on the circumstances, a vacant home endorsement or a specialized vacant property policy may be needed.

Sources
  1. Interview with Anna Blood. Blood Law, PLLC

    Interview with Anna Blood. Blood Law, PLLC

  2. Interview with Matthew Clark. The Clark Law Office

    Interview with Matthew Clark. The Clark Law Office

  3. Interview with Janet Ruiz. III

    Interview with Janet Ruiz. III

  4. Force-Placed Insurance: The Costly Mistake Every Homeowner Should Avoid. Residential Mortgage

    Force-Placed Insurance: The Costly Mistake Every Homeowner Should Avoid. Residential Mortgage